Roof Insurance Claims in Oklahoma
Understand the gap between a roof replacement cost and an insurance payment, including deductibles and depreciation.
Roof insurance payments and the project cost
A roof project total and an insurance payment are not the same number. A covered loss can still leave a deductible, depreciation that is not recoverable, or work that falls outside the policy’s covered scope.
The roof inspection establishes condition and repair options. The insurer determines coverage under the policy. Keeping those jobs clear makes the claim conversation easier without promising that a new roof will be paid for.
The roof and claim follow different decisions
Protect people and limit further damage
Keep clear of unsafe areas. Necessary temporary protection is different from completing permanent repairs before the insurer has assessed the loss. The insurer’s instructions and receipts matter.
Establish the roof condition
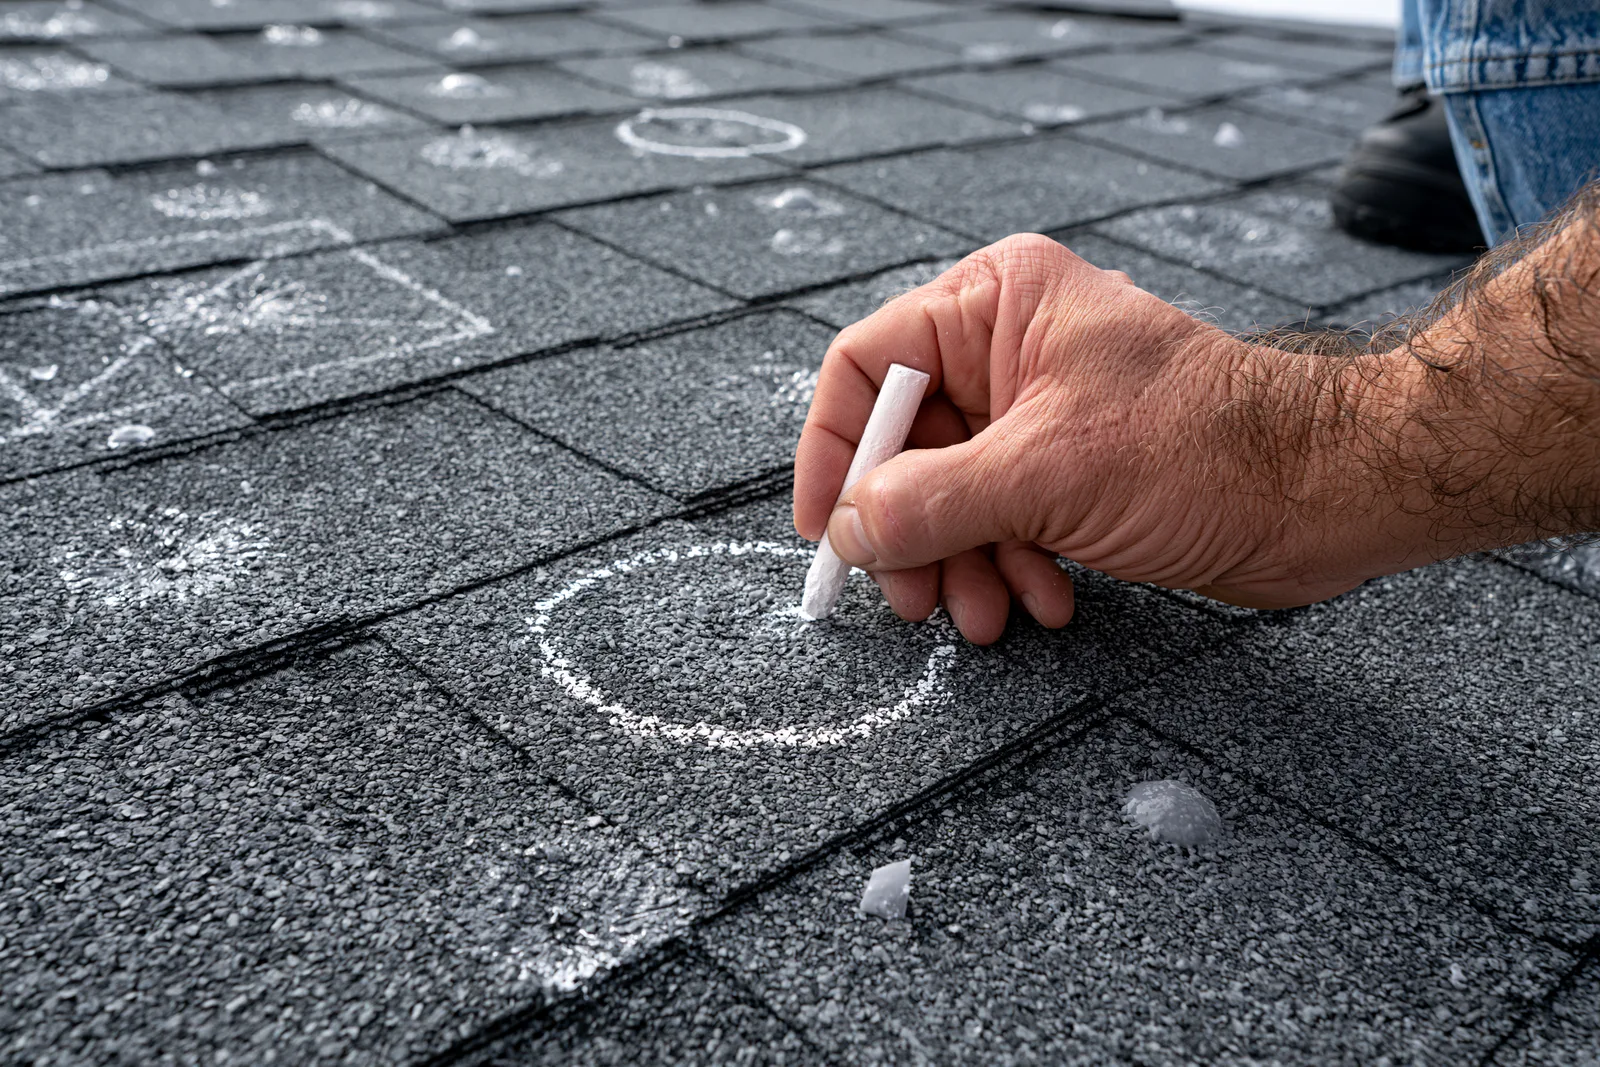
The inspection identifies visible damage and the proposed roofing scope. A nearby storm report provides timing context, not proof of damage or a coverage decision.
Apply the policy to the scope
Deductible, valuation method, exclusions and limits determine the payment. The roofing proposal and insurer’s allowed scope may need to be reconciled without assuming every item is covered.
Understand the payment terms
The Oklahoma Insurance Department FAQs explain ACV and replacement-cost roof settlements. The actual policy, including roof-specific provisions, controls.
| Term | What it means | Effect on the owner’s budget |
|---|---|---|
| Deductible | The applicable portion of a covered loss borne by the policyholder. | It remains part of the owner’s responsibility. Wind/hail terms can differ from other losses. |
| Actual cash value | Replacement cost reduced by depreciation under the policy. | The payment can be less than the cost to install a replacement roof. |
| Replacement cost coverage | Coverage based on repair or replacement under the policy’s terms. | An initial depreciated payment may be followed by additional payment after required conditions are met. |
Why the first payment may not be the final payment
For an illustrative covered replacement of $12,000, a $2,000 deductible and $3,000 of depreciation could leave an initial $7,000 payment. Under qualifying replacement-cost coverage, the $3,000 may be recoverable after the policy conditions are met. Under ACV-only coverage, it may remain part of the owner’s cost. This is arithmetic to explain the terms, not a prediction of a claim.
A percentage deductible is normally based on the specified coverage amount, not the cost of the roof repair. The policy’s declarations and endorsements establish the actual calculation. The insurance company or agent can explain those policy terms.
Roof Insurance FAQs
Does an inspection mean I should file a claim?
No. Findings establish condition. Whether to claim depends on the cause, repair scope, deductible and policy. Ordinary wear does not become storm damage because a roof is old.
Can the roof be repaired while the claim is being handled?
Necessary temporary protection may be appropriate, while permanent storm damage repairs need to be coordinated with the insurer’s assessment and instructions.
Can weather records prove a claim?
No. They report events at recorded points or tracks. They do not establish what happened to an individual roof, and an inspection cannot date every mark.